DS Securities Says Semiconductor, Won Shock Already Priced In — Points to 2027 HBM Prices
True
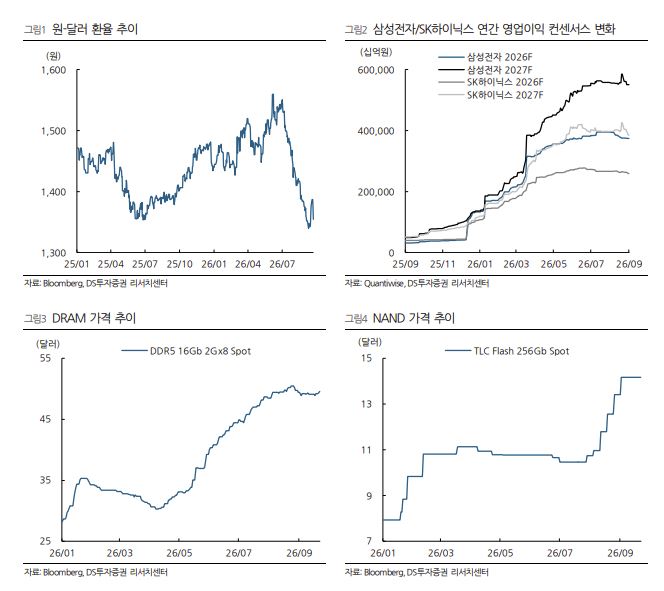
DS Securities has assessed that the negative impact of the semiconductor downturn and currency shocks on Korean chipmakers is already a known factor, arguing that the market's focus should shift to HBM prices in 2027.
Known Headwinds, Not New Risks
According to the DS Securities report, the semiconductor sector's slump and the recent volatility in the won-dollar exchange rate represent adverse factors that are already known to investors rather than emerging surprises. The securities firm framed these headwinds as largely reflected in current valuations, suggesting limited additional downside from these sources alone.
Focus Shifts to 2027 HBM Pricing
The report instead directs attention to HBM price trends in 2027, positioning them as the key variable for the sector's outlook. HBM has become a central profit driver for Korean memory makers such as SK hynix and Samsung Electronics amid AI-driven demand. The report does not specify an expected price direction or magnitude for 2027 HBM pricing, leaving that as an open question for investors to watch.
The claim, as reported, holds true.
- https://www.etoday.co.kr/news/view/2630110
- https://www.yna.co.kr/view/AKR20260929025000008
- https://www.mt.co.kr/stock/2026/09/29/2026092908435349662
- https://magazine.hankyung.com/business/article/202609290958b
- https://fred.stlouisfed.org/graph/fredgraph.csv?id=DEXKOUS
- https://www.smarttoday.co.kr/ko-kr/articles/112029
- https://img.etoday.co.kr/pto_db/2026/09/20260929074653_2394254_664_591.JPG
- https://d18r0a86za96sg.cloudfront.net/wp-content/uploads/2026/05/27132311/SK-hynix-HBM4_resized_01.jpg
- https://d18r0a86za96sg.cloudfront.net/wp-content/uploads/2026/05/27132314/SK-hynix-HBM4_resized_02.jpg

